Retirement income planning is different from building a retirement corpus. Once regular salary stops, the priority often shifts from accumulating money to creating a dependable cash flow that can support household expenses for decades. Two options Indian investors commonly evaluate for this purpose are annuity plans and Systematic Withdrawal Plans (SWPs) from mutual funds.
An annuity converts a lump sum into a stream of payments according to the chosen option. A mutual fund SWP works differently: money remains invested in a mutual fund, and a specified amount is periodically redeemed and paid to the investor.
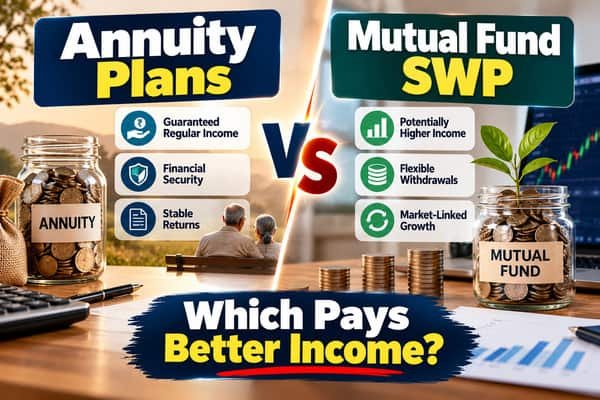
Annuities generally provide greater income certainty, particularly when a lifelong annuity is selected. SWPs provide greater flexibility and growth potential but expose the retirement corpus to market movements. Therefore, the option that “pays better” depends on whether better means guaranteed lifetime income, potentially higher withdrawals, inflation protection, liquidity or leaving money for heirs.
How Does an Annuity Plan Work?
An annuity is generally purchased from a life insurance company by paying a lump-sum purchase price. In return, the insurer provides periodic income according to the annuity option selected.
Payments may be available monthly, quarterly, half-yearly or annually, depending on the product.
Common annuity structures can include:
- Life annuity
- Joint-life annuity
- Annuity with return of purchase price
- Annuity guaranteed for a specified period and thereafter for life
- Other variants offered by the insurer
The income available can vary considerably between these options.
For example, an annuity without return of purchase price may offer a different payout from an option designed to return the purchase price to a nominee after the annuitant’s death.
How Does a Mutual Fund SWP Work?
A Systematic Withdrawal Plan is a facility through which an investor instructs a mutual fund to redeem units periodically.
Suppose a retiree has accumulated ₹50 lakh in a mutual fund and sets an SWP of ₹30,000 per month.
Every month, sufficient units are redeemed to provide ₹30,000.
The remaining units continue to stay invested.
If the portfolio earns returns exceeding withdrawals and other effects over a suitable period, the corpus can potentially last longer or grow. If withdrawals are high and investment performance is poor, the corpus can decline and may eventually be exhausted.
Unlike a lifetime annuity, an SWP does not inherently guarantee income for life.
Annuity Vs Mutual Fund SWP: Key Differences
| Factor | Annuity Plan | Mutual Fund SWP |
|---|---|---|
| Income certainty | High under guaranteed annuity terms | Depends on available corpus and market performance |
| Lifetime income | Available with suitable annuity options | Not guaranteed |
| Market risk | Generally borne by insurer for guaranteed payout | Investor bears investment risk |
| Liquidity | Usually limited | Generally much higher |
| Withdrawal flexibility | Limited after purchase | SWP amount can generally be changed/stopped |
| Growth potential | Limited under conventional guaranteed annuity | Depends on underlying mutual fund |
| Inflation protection | Can be limited unless product structure addresses it | Growth assets may help over long periods |
| Capital for heirs | Depends on annuity option | Remaining corpus belongs to investor/estate |
| Tax treatment | Annuity income generally taxable as applicable | Tax generally arises on gains in redeemed units under applicable rules |
| Best suited for | Income certainty | Flexible retirement withdrawals |
Which Can Provide Higher Monthly Income?
The answer depends on the assumptions used.
An annuity rate determines the income available against the purchase price. Once the annuity is purchased, payments are made according to the selected contract.
An SWP allows the investor to choose a withdrawal amount.
This means someone with ₹50 lakh could technically set an SWP of ₹50,000, ₹75,000 or even more per month.
But a higher withdrawal does not mean the investment is producing that much income.
Part of the withdrawal may simply be the investor’s own capital being returned.
This distinction is critical.
A high SWP can look attractive for several years while quietly reducing the number of units and eventually exhausting the retirement corpus.
Therefore, monthly payout alone is not enough to determine which option is superior.
Annuities Solve Longevity Risk
One of the greatest uncertainties in retirement planning is lifespan.
A person retiring at 60 may need income for another 10 years—or another 35 years.
With a suitable lifetime annuity, the insurer continues making contracted payments for as long as the covered annuitant remains alive, subject to the chosen option.
This transfers longevity risk to the insurer.
An SWP leaves that risk with the investor.
If withdrawals are too high, investment returns are disappointing or retirement lasts longer than expected, the corpus can become insufficient.
For retirees worried primarily about never running out of essential income, this is a major advantage of annuities.
Inflation Is the Challenge for Fixed Annuity Income
Income certainty does not necessarily mean purchasing-power certainty.
Suppose retirement expenses are ₹50,000 per month today.
If living costs rise over the years, the same ₹50,000 will purchase considerably less in the future.
A fixed annuity payment can therefore become less adequate as retirement progresses.
This is where a carefully structured investment portfolio can provide an advantage.
Mutual funds with appropriate exposure to growth assets may generate returns that help the retirement corpus respond to inflation over long periods.
However, higher expected returns generally require accepting greater investment risk.
SWPs Offer Much Greater Flexibility
Retirement expenses rarely remain perfectly constant.
A retiree may need additional money for:
- Home renovation
- Family events
- Travel
- Emergency expenses
- Large purchases
- Other unexpected requirements
With mutual funds, the investor generally retains control over the remaining corpus.
The SWP can usually be increased, reduced or stopped, and additional redemptions can be made subject to scheme conditions and applicable exit loads or taxes.
An annuity is far less flexible after purchase. Once the purchase price has been committed to the selected annuity option, reversing the decision may be difficult or unavailable except where specifically permitted.
Sequence-of-Returns Risk Matters With SWPs
Average return is not the only risk faced by retirees using mutual funds.
The order in which returns occur can be extremely important.
Imagine two retirees earn similar average returns over 15 years. One experiences strong market performance during the first five years, while the other suffers a major decline immediately after retirement.
The second retiree may need to redeem more units at depressed values to maintain the same monthly withdrawal.
Those units are then permanently removed from the portfolio and cannot participate in a subsequent market recovery.
This is known as sequence-of-returns risk.
Maintaining suitable debt or liquid reserves rather than relying entirely on volatile assets can help manage this risk.
Which Option Leaves More Money for Family?
Mutual fund SWPs have a clear structural advantage when estate flexibility is important.
Whatever investment remains belongs to the investor and can ultimately pass according to the applicable succession and nomination framework.
With annuities, what beneficiaries receive depends on the selected option.
Some annuities provide only lifetime payments, while others can include:
- Joint-life benefits
- Return of purchase price
- Guaranteed payment periods
Adding survivor or capital-return features can affect the annuity payout available.
Therefore, retirees should not compare annuity rates without checking what happens after the annuitant’s death.
Tax Treatment Can Affect Spendable Income
Taxation is another significant difference.
Annuity payments are generally taxable in the recipient’s hands according to applicable income-tax rules.
An SWP is a series of redemptions from mutual fund units.
The entire withdrawal is not automatically treated as investment profit. Each redemption can include invested capital as well as capital gain, and the gain is taxed according to the applicable rules for that category of mutual fund.
As tax rules and individual circumstances can change, retirement-income comparisons should be based on post-tax cash flow, not merely the amount credited each month.
A Combination Can Work Better Than Choosing Only One
Retirees do not necessarily need to place their entire retirement corpus into either an annuity or mutual funds.
A combination can address different risks.
For example, part of the corpus could be used to create predictable lifetime income covering essential expenses such as:
- Food
- Utilities
- Basic housing costs
- Regular household expenditure
The remaining corpus could stay invested in an appropriately diversified portfolio and support an SWP for discretionary and inflation-sensitive expenses.
This approach combines some income certainty with liquidity and growth potential.
The appropriate allocation depends on retirement expenses, other pension income, assets, dependants and risk tolerance.
Which Pays Better Retirement Income?
If “better” means guaranteed income that can continue for life, an appropriate annuity has the stronger proposition.
If “better” means flexibility, access to capital and the possibility of growing withdrawals over a long retirement, an appropriately managed mutual fund SWP can be more suitable.
Annuities can be especially useful for retirees who cannot afford to have essential living expenses depend heavily on market performance.
SWPs can suit retirees who have sufficient capital, can tolerate market fluctuations and want greater control over their money.
Rather than asking only which provides the highest starting monthly payout, retirees should compare how each option performs against four risks: living too long, inflation, market volatility and unexpected need for capital.
FAQs
Q1. Is income from an annuity guaranteed for life?
A. A lifetime annuity is designed to make payments for the lifetime of the covered annuitant according to the selected option and contract. Other annuity structures may work differently, so the exact benefit should be checked before purchase.
Q2. Can an SWP continue for my entire retirement?
A. It can continue as long as sufficient units and value remain in the investment. There is no automatic lifetime guarantee. The sustainability of an SWP depends on the starting corpus, withdrawal rate, investment returns, market sequence, costs and duration of retirement.
Q3. Can I increase my mutual fund SWP when inflation rises?
A. Generally, investors can modify or establish withdrawal instructions according to the mutual fund’s operational rules. However, increasing withdrawals also increases pressure on the corpus, so any increase should be evaluated against portfolio value and expected retirement duration.
Q4. Should retirees use both an annuity and an SWP?
A. For some retirees, using both can provide a useful balance. An annuity can create predictable income for essential expenses, while a diversified investment portfolio with an SWP can provide liquidity and potential long-term growth. The appropriate mix depends on the retiree’s income needs, other assets and ability to tolerate investment risk.